Personal Finance – Managing Money and Building a Financial Plan
This product overview guides readers through managing money more effectively and building a comprehensive financial plan that supports both everyday stability and long-term goals. It outlines the key pillars of personal finance—budgeting, saving, investing, debt management, insurance, and retirement planning—and how they interact with income, credit health, and financial literacy. You’ll find practical steps, examples, and checklists designed to help you set measurable financial goals, prioritize actions, and tailor plans to your income, family, and risk tolerance. Whether you are just starting out or revising an existing strategy, applying disciplined habits and smart projections can increase resilience and clarity while reducing uncertainty.
What is personal finance?
Personal finance is the practice of earning, spending, saving, investing, protecting against risk, and planning for long-term financial well-being. It covers how you allocate income today to meet immediate needs while building a foundation for tomorrow. At its core is the time value of money—the idea that a dollar you save and invest now can grow through compounding, while delaying consumption carries a cost. Effective personal finance also involves understanding risk, taxes, and opportunity costs, so you can make informed choices without sacrificing essential living standards. It includes activities like budgeting, tracking expenses, and establishing clear financial goals that align with your values and life stage.
Five core components shape a solid personal-finance plan: budgeting, saving, investing, debt management, and risk protection through insurance, plus a focus on retirement planning. Budgeting helps you describe where money goes, ensuring expenses stay below income and that debt does not spiral. Saving creates a cushion for emergencies and future purchases, often via automatic transfers. Investing seeks to grow wealth over time by participating in markets, with diversification helping manage risk. Debt management reduces high-cost liabilities and preserves flexibility, while insurance guards against unforeseen events. Retirement planning ties the pieces together, translating current behavior into a sustainable standard of living in later years, with attention to inflation and healthcare costs.
A well-designed personal-finance framework also requires discipline, regular reviews, and literacy. Tracking progress against goals, adjusting for changes in income or expenses, and learning basic concepts like credit scores, liquidity, and risk tolerance help maintain momentum. Tools such as budgets, calendars, and simple calculators make the process tangible rather than theoretical. By integrating these elements, you can steadily improve financial resilience and create a measurable pathway from today’s decisions to tomorrow’s outcomes.
Core components: budgeting, saving, investing, debt, insurance, retirement
The core components of personal finance are not isolated tasks; they interlock to form a cohesive plan that grows with your income and life changes. Below are the key areas that work best when aligned with your goals and timeline.
- Budgeting basics
- Saving strategies
- Investing essentials
- Debt management tactics
- Insurance considerations
- Retirement planning basics
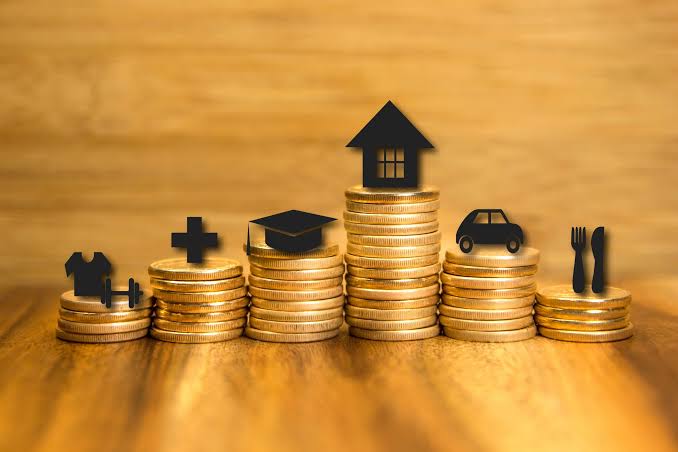
Viewed together, budgeting, saving, investing, debt management, insurance, and retirement planning create a flexible framework that adapts to milestones, emergencies, and evolving financial goals.
Budgeting basics
Budgeting basics involve documenting income and expenses, then allocating funds toward essentials and goals. Start by listing sources and fixed costs such as housing and utilities. Identify discretionary categories you can adjust, like dining out, and set limits that align with priorities. Use transfers to move money into savings or debt payments, and review your plan to catch changes and keep spending honest. A repeatable process reduces stress and increases control over financial future.
Saving strategies
Saving strategies emphasize consistency, automation, and purpose. Start with an emergency fund equal to three to six months of essential expenses, then build separate goals for short- and mid-term needs. Automate transfers to a high‑yield savings account and gradually increase contributions as income grows. Use milestones to celebrate progress and stay motivated. Avoid lifestyle inflation by keeping discretionary spending in check, and periodically review expenses to reallocate savings toward more impactful targets over time consistently.
Investing essentials
Investing essentials revolve around diversification, low costs, and a long horizon. Start with a simple allocation aligned to risk tolerance, then rebalance periodically to maintain target diversification. Favor broad-market index funds or exchange-traded funds (ETFs) over single-stock bets to reduce risk and fees. Automate contributions, stay focused on long-term growth, and ignore short-term noise. Remember that compounding works best when investments stay invested, taxes are managed, and your plan adapts as life changes over time.
Debt management tactics
Debt management tactics focus on reducing liabilities efficiently while preserving liquidity. Start by listing all debts, noting interest rates and minimum payments, then prioritize repayment using either the avalanche (highest rate first) or the snowball (smallest balance first) approach. Consider consolidation if appropriate and affordable, negotiate lower interest or fees, and keep credit utilization low to protect your score. Build an automated plan that accelerates payoff while maintaining essential spending, emergencies funds, and investment contributions.
Insurance considerations
Insurance considerations evaluate risk and affordability to protect assets and income. Begin with core coverages such as health, life, disability, homeowners or renters, and auto, then assess gaps based on dependents, income, and liabilities. Compare policy features, deductibles, and riders, favoring simplicity and transparency over complexity. Regularly review coverage as life changes—marriage, children, home purchases, or career shifts—so your protections evolve without redundancy or excessive premiums. Ask about exclusions, waiting periods, and claim procedures upfront.
Retirement planning basics
Retirement planning basics focus on estimating needs, building savings, and coordinating benefits. Start by projecting expenses in retirement, accounting for inflation, healthcare, housing, and lifestyle. Identify income sources such as Social Security, pensions, or employer-sponsored programs, and decide withdrawal strategies that preserve purchasing power. Then select an investment approach that balances growth and safety as you age, and adjust asset allocation as life stages change. Revisit goals, monitor fees, and ensure beneficiaries and plans align.
Who should care and why
Anyone who earns income or manages money should care about personal finance. Different life stages bring different priorities: students and new professionals benefit from building healthy money habits, managing debt wisely, and establishing credit. Families must plan for housing, education, healthcare, and protecting dependents. Mid-career individuals often focus on maximizing savings, paying down debt, and preparing for kids’ needs or career changes. Late-career and retirees concentrate on sustainable withdrawals, healthcare costs, and preserving wealth. Business owners and freelancers require cash-flow discipline and diversified income streams to weather fluctuations.
Ultimately, the motivation is universal: security, independence, and the ability to fund meaningful life milestones. Those who actively improve financial literacy, track progress, and adjust to changing circumstances tend to experience greater confidence and resilience. The audience broadens when you recognize that personal finance is not about perfection, but about consistent, informed choices aligned with values and goals.
Common misconceptions and risks
Common misconceptions include the belief that you need a lot of money to start investing, that budgeting is inherently restrictive, or that credit scores don’t matter. In truth, small, regular investments can grow substantially through compounding; budgeting can unlock financial freedom by revealing choices, and a healthy credit profile enables better loan terms. Other risks involve market fluctuations, inflation eroding purchasing power, and life events that disrupt plans. An emergency buffer, disciplined saving, and diversified investments help mitigate these threats.
Additional risks include underestimating healthcare costs in retirement, overreliance on a single income source, and creeping lifestyle inflation as income rises. To counter these, start with a realistic plan, automate savings and debt payments, diversify investments, and educate yourself on tax implications and fee structures. Regularly revisit goals, monitor progress, and adapt to changes in income, family size, and economic conditions. A proactive approach reduces uncertainty and strengthens financial resilience.
Practical steps to address misconceptions and risks include starting small but consistently investing, using low-cost options, tracking progress with simple metrics, and seeking trustworthy sources to build financial literacy. By grounding decisions in data and ongoing learning, you can avoid common traps and maintain momentum toward long-term financial goals.
Key Features and Benefits
Managing money effectively starts with clarity about your financial goals and the habits that support them. This guide highlights practical steps for budgeting, saving, investing, debt management, and retirement planning, so you can build a sustainable plan that fits your life. You’ll learn how to create a personalized budget, grow an emergency fund, and monitor progress toward long-term financial goals like retirement and education funding. By integrating financial literacy with actionable tools, you can improve your credit score, diversify income streams, and stay adaptable as circumstances change.
Budgeting methods and tools
A practical budget framework starts by mapping every source of income, identifying fixed obligations, estimating variable costs, and tying these elements to clear financial goals so you can act with intentional restraint rather than reactive spending, ensuring every dollar serves a purpose that moves you toward milestones like emergency funding and retirement readiness.
Then you choose a budgeting method that fits your personality and life rhythm, whether you favor predictable envelopes, a flexible percentage rule, or a zero-based plan that guarantees accountability, reduces waste, and creates a transparent, adjustable roadmap for daily decisions and long-term progress.
- Zero-based budgeting assigns every dollar a specific purpose at the start of the month, aligning spending, savings, and debt payments to your income so nothing remains unassigned or wasted.
- 50/30/20 budgeting guides your money by allocating 50% to needs, 30% to wants, and 20% to savings or debt reduction, creating predictable patterns, reducing friction, and fostering long-term discipline.
- Envelope budgeting physically or digitally isolates funds for categories, offering real-time visibility into spending pace and helping you avoid overdrawn accounts or impulse purchases, consistently over time and every month.
- Incremental budgeting uses small, frequent adjustments to expenses and savings, enabling you to test what works, learn from short-term results, and gradually improve your overall financial health and long-term confidence.
Whatever method you adopt, start with a one-month pilot, document deviations from plan, and adjust categories, thresholds, and goals as you gain insight into actual spending patterns and savings capacity, leveraging apps or spreadsheets to visualize results and stay motivated.
Pair budgeting with automatic transfers to savings and debt payments, review progress monthly, and align your budgets with broader aims like emergency funding, retirement planning, education funding, and building additional income streams to strengthen financial resilience.
Saving strategies and emergency funds
Saving strategies and emergency funds are two sides of the same coin: you need both the discipline to save consistently and the safety net that protects you during unexpected events.
Start by naming a target for an emergency fund, commonly covering three to six months of essential living costs, and adjust this target based on job stability, family size, and debt load. Automate monthly transfers into a high-yield savings account so the money grows without requiring daily effort, and designate sub-accounts for specific goals like housing, education, or medical needs to avoid commingling funds.
Beyond emergency funds, adopt a steady saving cadence that supports short-, medium-, and long-term goals. Consider tax-advantaged accounts when available, maximize employer matches, and revisit contribution levels annually to keep pace with rising living costs. If cash flow is tight, pursue small, recurring savings actions such as rounding up purchases, pausing nonessential subscriptions, and consolidating high-interest debt where possible. Track your progress with simple metrics like the savings rate, time to goal, and balance growth, while staying curious about new saving techniques and tools to improve financial literacy.
Finally, recognize that saving is not only about money but also about building confidence to handle life changes and to fund opportunities that improve well-being and security for you and your loved ones.
Investment basics: risk, return, diversification
Investment basics combine risk awareness, expected return, and diversification to build a resilient portfolio aligned with time horizon and goals.
| Asset Class | Typical Return Range (long term) | Risk Level | Liquidity | Example Vehicles |
|---|---|---|---|---|
| Cash and Cash Equivalents | 0–2% | Low | High | Savings accounts, money market funds |
| Bonds and Fixed Income | 2–5% | Medium | Moderate | Treasury, municipal, corporate bonds |
| Stocks and Equity | 6–10% (long term) | High | High | Indexed funds, mutual funds, ETFs |
| Real Estate and Alternatives | 4–8% | Medium-High | Moderate | REITs, real estate funds, commodities |
These ranges reflect long-term expectations and can vary with market cycles and inflation. Diversification across asset classes and investing regularly through automatic contributions can smooth returns and reduce risk, helping you stay aligned with your financial goals and retirement planning timeline.
Debt management and credit score impact
Debt management and credit score impact address how you can reduce interest costs and protect credit health while paying down debt strategically.
Two common payoff strategies are the avalanche method (highest interest first) and the snowball method (smallest balance first); both aim to speed up repayment while preserving essential living costs. Consider refinancing or consolidating high-interest debt if it lowers payments or reduces total interest over time, but be sure to compare annual percentage rates, fees, and potential impact on your credit score.
Pay on time and keep credit utilization reasonable to protect or improve your score, which influences loan approvals, interest rates, and insurance premiums. Build a realistic repayment plan that fits your income volatility, and avoid taking on new debt unless it clearly supports long-term financial goals, such as income growth or retirement planning.
Plans, Specifications, and Competitive Comparisons
Plans, specifications, and competitive comparisons form the backbone of a practical personal finance approach. This section helps you map out financial horizons, evaluate concrete plan options, and benchmark products against clear criteria. By outlining short-, mid-, and long-term plans, you can align budgets, savings goals, and investment strategies with your real-life priorities. We also compare common financial products to illuminate trade-offs around fees, liquidity, and tax implications. Use this guide to build a coherent financial plan that supports your long-term goals while staying adaptable to life changes.
Types of financial plans: short-term, mid-term, long-term
A financial plan is commonly described as three horizons: short-term, mid-term, and long-term. Each horizon serves different goals, timeframes, and levels of risk, and they work best when aligned with your income streams and overall financial literacy. A well-structured plan guides budgeting decisions, helps you prioritize saving, and sets a clear path for investing that matches your stage in life.
Short-term plans cover the near future and emphasize liquidity, debt management, and emergency readiness. The focus is on building a cash cushion while maintaining the flexibility to respond to unexpected expenses or opportunities. Mid-term plans stretch across one to five years and are ideal for goals such as a down payment, a major purchase, or funding education. These plans balance saving with cautious growth, typically combining high-yield savings with conservative investments and insurance protections.
Long-term plans extend five years or more and emphasize wealth accumulation and retirement planning. The power of compounding, asset allocation, and tax-advantaged accounts becomes central as you diversify investments and manage risk over time. A robust long-term plan also calls for regular reviews of asset mix, contribution rates, and progress toward financial goals, while planning for potential life changes and inflation.
Across horizons, practical steps include establishing a realistic budget, monitoring credit score, and building an emergency fund. Your plan should include clear milestones and a mechanism to adjust when income changes, expenses rise, or goals shift. By connecting budgeting, saving, investing, and debt management under a unified framework, you can improve financial literacy and create a resilient strategy for long-term security.
In practice, many people start with a simple baseline plan and then layer in more sophistication as income grows and goals become more ambitious. Schedule periodic reviews, automate essential contributions, and use a consistent method to measure progress toward financial goals. A thoughtful approach to plans across horizons helps you stay on track while remaining flexible in the face of life events and market changes.
Choosing a plan based on life stage
Choosing a plan based on life stage means matching your cash flow, risk tolerance, and goals to where you are in life. The following framework highlights common stages and practical actions to optimize budgeting, saving, and investing.
- Establish a simple monthly budget, automate savings, and tackle high-interest debt early to build a solid financial foundation for an unpredictable start to your career.
- Prioritize an emergency fund covering 3–6 months of essential expenses, and begin a basic investing plan to grow wealth while maintaining liquidity for future opportunities.
- Plan for increasing expenses and potential life changes by gradually boosting savings rates as income grows, enabling education, housing, and healthcare goals without compromising daily cash flow.
- Track credit health and debt levels, understanding how timely payments and utilization affect scores while building a strategy for manageable debt reduction aligned with future borrowing needs.
Life-stage planning also benefits from scaling contributions as earnings increase, staying attentive to retirement readiness, and revisiting priorities when major events occur. The aim is to protect your essential needs while setting you up for longer-term growth, using budgeting and saving as the foundation for smarter investing and informed decisions about when to borrow or accelerate debt payoff.
Early career and budgeting basics
Early career and budgeting basics — at the start of your financial journey, the priority is to establish discipline and momentum. Begin with a realistic budget that tracks income and essential expenses, then automate savings to remove the friction from paying yourself first. Target an emergency fund that covers three to six months of living costs, a buffer that absorbs shocks without forcing you into high-interest debt. Start with a modest investment plan focused on broad diversification and low fees, and gradually increase contributions as your paycheck grows. Keeping debt under control, especially high-interest balances, contributes directly to your credit score and overall financial health, which in turn supports future borrowing for education, housing, or business needs.
Family formation and saving goals
Family formation and saving goals — as life events expand your expenses, adjust your plan to prioritize education savings, housing costs, and health coverage. Build a comprehensive budget that accounts for childcare, meals, and transportation, and maintain a robust emergency fund to weather unexpected costs. Consider tax-advantaged accounts for education and retirement, and set aside additional savings for a family safety net. Maintaining a plan to reduce high-interest debt remains important, but you can steer cash toward building assets that support stability and opportunities for your children.
Career growth and debt management
Career growth and debt management — when earnings rise, increase retirement contributions and diversify investments to benefit from compounding over time. Create a debt reduction strategy that targets high-interest loans while preserving liquidity for emergencies. Use a budget to capture raises and bonuses, and redirect a portion into credit-building moves and investment accounts. Regularly review insurance protections and adjust coverage as family needs change. This stage also benefits from developing additional income streams to accelerate progress toward major goals such as homeownership or education funding.
Pre-retirement planning and wealth transfer
Pre-retirement planning and wealth transfer — as retirement nears, emphasize maximizing tax-advantaged savings, optimizing withdrawals, and protecting capital against volatility. Increase contributions to retirement accounts where appropriate, consider catch-up provisions, and plan for healthcare costs in retirement. Develop a plan for transferring wealth or assets to heirs, including estate planning basics, beneficiary designations, and risk-management strategies. Keep debt low and liquidity available for sudden needs, and maintain a flexible strategy to adapt to changing markets and personal circumstances.
Comparing financial products: savings accounts, brokerage, retirement accounts
When choosing between savings, brokerage, and retirement accounts, understanding structure, fees, and tax treatment helps you optimize growth and liquidity. The table below summarizes key differences and practical use cases.
| Product | Typical Fees | Liquidity | Tax Benefits | Best Use |
|---|---|---|---|---|
| Savings accounts | Low or no fees; some banks charge maintenance | Very liquid; easy access to funds | Interest income taxed as ordinary income; some accounts offer tax-advantaged options | Emergency funds and short-term goals |
| Brokerage accounts | Trade commissions or platform fees; expense ratios | High liquidity for many assets | Capital gains taxes; tax-efficient strategies vary by asset | Long-term investing and diversification |
| Employer-sponsored retirement plans | Typically no direct fees; investment fund fees apply | Access limited before distributions; some options allow loans | Tax-deferred growth; employer match enhances value | Long-horizon retirement savings and tax planning |
| Individual Retirement Accounts (IRAs) | Annual contribution limits; fund and trading fees | Withdrawals are restricted before certain ages | Tax-advantaged growth; Traditional vs Roth have different rules | Dedicated retirement funding with tax benefits |
These product comparisons provide a starting point for decisions, but align choices with your financial goals, risk tolerance, and time horizon.
Offers, Pricing, Onboarding, and Support
This section breaks down how personal finance services are priced, how onboarding works, and the kinds of support you can access as you manage money and build a financial plan. You will learn how to compare offers, understand fee structures, and identify which setup steps are required to get started. We compare traditional advisors, robo-advisors, and self service tools so you can match the model to your financial goals. From promotions and welcome offers to ongoing fees, tying onboarding to long term outcomes helps you avoid surprises. Finally, you will find practical tips for negotiating better terms and selecting the right combination of services to support budgeting, saving, and investing.
How to choose financial services and fees to watch
Choosing financial services and understanding the fee landscape starts with a clear map of your needs and goals. Fees can erode returns over time, especially when compounding is involved, so it is critical to separate the sticker price from the true cost of ownership. Common models include flat monthly retainers, assets under management percentages, commissions on products, and performance based fees. Some services charge mixed structures, adding onboarding or account maintenance fees. In addition to explicit charges, consider implicit costs such as fund expense ratios, bid ask spreads, and tax inefficiencies from certain investment choices. When budgeting and saving, a clean fee profile helps your money work harder toward your objectives, whether retirement planning or funding short term goals.
Next, compare costs using a simple framework: identify all fees, estimate how often you will incur them, and translate them into an annualized percentage of your assets or a monthly cash outlay. For a long horizon, even small differences compound into meaningful gaps in wealth. Look beyond the headline rate and check for minimums, waived fees during promotions, and ongoing maintenance charges. Pay attention to fund level costs if the service invests in mutual funds or ETFs, because those expense ratios directly reduce returns. Also consider whether trailing commissions or product based payments could bias advice or recommendations, and weigh that against your financial goals.
Request a written fee schedule and run side by side comparisons for your expected activity level. Create hypothetical scenarios using your current and projected balances to see how costs scale with your investments or transactions. Ask whether fees decrease at higher balances, how onboarding rates change after a trial period, and whether there are hidden costs for transfers, withdrawals, or account inactivity. Seek clarity on service levels: is the advisor charging a flat fee for planning only, or is ongoing management included? For budgeting, saving, and debt management, you may prefer transparent, low cost options with predictable charges. For long term investing and retirement planning, prioritize models with clear, low fees and robust performance data over flashy promises.
Ultimately, the right price is the price that aligns with your financial literacy and goals. Lower cost, high clarity options often outperform pricier choices when outcomes are compared over time. Use your understanding of fee structures to choose products and services that empower you to meet your financial goals without sacrificing control or flexibility.
Onboarding: setting up accounts and linking finances
Onboarding starts before you sign up. Before opening an account, review the service scope, privacy policy, and the documentation you will need to verify your identity and link finances. Typical requirements include a government issued photo ID, proof of address, and in some jurisdictions a tax identification number. You may also be asked to answer questions about risk tolerance and financial goals to tailor the experience. Having these items ready speeds up the process and helps prevent delays in setting up your dashboard, connecting bank accounts, and enabling the initial transfers.
Step by step, the setup usually looks like this: choose your product or plan, complete the identity verification, and accept consent for data sharing and security measures. Then create login credentials, enable two factor authentication, and choose security preferences such as alert notifications. Next, link external bank accounts and retirement plans through a secure connection, which may involve micro deposits to confirm ownership. Finally, configure your budget categories, set initial goals, and decide how often you want to receive performance updates or reports.
Bring your paperwork, be ready to confirm funding sources, and decide how you want to allocate initial investments. If you plan to transfer balances from other providers, ask about transfer timelines and any associated fees. During onboarding you should also review privacy controls and decide how much personal data you are comfortable sharing for personalized insights. Expect a short onboarding checklist and a first progress report within the first week, with tips on setting up emergency funds, retirement planning milestones, and debt management goals.
To keep onboarding smooth, set aside dedicated time, use secure devices, and verify that two factor authentication is active. Make sure you understand the terms for data usage, refunds, and service levels, and note the expected timeframe for account activation and first transfers. Having these items ready helps you start budgeting, saving, and investing with confidence from day one.
Ongoing support: advisors, robo-advisors, and self-service resources
After onboarding, you have several paths for ongoing support, each with its own balance of cost, control, and customization. Human advisors offer fiduciary guidance, personalized plans, and complex tax or estate planning help, typically charging a fee based on assets or a flat planning retainer. Robo-advisors automate diversified portfolios at low cost and scale well for straightforward saving and investing, with rules based rebalancing and goal tracking. Self-service resources, including budgeting tools, calculators, and educational content, empower you to adjust plans and learn while you invest.
Use human advisors for strategic decisions such as retirement planning, tax optimization, or when your financial situation includes multiple income streams and significant debt. Consider robo-advisors for cost efficiency, automatic rebalancing, and a simple, steady path toward long term goals. For most people, a hybrid approach works best: a core robo-advisor with access to occasional human consults for questions that require professional judgment.
Self-service resources are valuable for ongoing literacy and quick adjustments. Personal finance education helps you stay aligned with your financial goals and ensures you do not rely solely on automated tools. Track progress with monthly reviews, update goals as life changes, and use built in simulations to see how early saving, emergency funds, and debt management strategies affect overall outcomes.
Whichever model you choose, set expectations early: define the service level, determine how often you receive updates, and schedule periodic reassessments to keep costs predictable and your plan on track.
Promotions, fee structures, and negotiation tips
Promotions and welcome offers are common entry points to trial a service. Look for temporary fee waivers, introductory discounts, and bonus credits that reduce the first year cost. Some providers also offer reduced minimums or free planning for a limited time, which can be attractive if you are just starting to build a budget or begin investing.
Fee structures vary by provider, and promotions can mask the true ongoing cost. After the introductory period, fees may revert to standard rates based on assets, transactions, or service levels. Always compare the post promotion price to your budgeting and saving plan, and run the numbers to see how long the savings last and what the total cost would be over your investing horizon.
Negotiation tips include asking for a permanent fee reduction, bundling multiple services, or requesting a loyalty or grandfathered rate. It helps to demonstrate your commitment to a long term relationship, reference competing offers, and request a clear plan for how your costs will change with balance growth. Be prepared to trade preferences such as access to human advisors for a lower fee or to accept higher minimum investments if the price drops.
Read the fine print on any promotions to understand eligibility, maintenance requirements, withdrawal penalties, and how performance is measured. If a provider cannot justify the long term value, walk away and compare alternatives. The goal is to secure a sustainable, transparent pricing structure that aligns with your financial goals and financial literacy over time.